Your first months in Geneva
The insurance checklist for newcomers
Some insurance is compulsory in Switzerland, some is expected in practice, and some depends on your situation. Here is what matters when you settle in Geneva.
Health insurance (LAMal): compulsory
You must take out basic health insurance within three months of arriving. Cover is backdated to your arrival date, so you pay the premiums from that date anyway; joining late can also cost a surcharge.
Premiums are per person and do not depend on your income. The deductible (from CHF 300 to CHF 2,500) and the insurance model (family doctor, HMO, telemedicine) change the price a lot. Staff of international organisations may be exempt: we check your status first.
Home contents and personal liability: expected
Not required by law, but most landlords and letting agencies ask for liability insurance when you sign a lease. It covers damage you cause to the flat or to other people.
Home contents insurance protects your belongings against fire, water damage and theft.
Rental deposit: an insurance alternative
Landlords can ask for up to three months' rent as a deposit. Instead of blocking that cash in a bank account, a rental guarantee insurance can provide it for a yearly premium.
Accident, car and family
If you work at least 8 hours a week, your employer covers you against accidents, including in your free time. Car liability insurance is compulsory once your car is registered in Geneva. With a family, check what happens to your income if you fall ill or become disabled.
Pensions
The Swiss three-pillar system in a nutshell
1st pillar: state pension (AVS/AHV)
Compulsory and deducted from your salary. It covers basic needs in retirement, disability and for surviving relatives.
2nd pillar: occupational pension (LPP/BVG)
Your employer's pension fund, compulsory above a minimum salary. Voluntary buy-ins can improve your pension and reduce your taxes.
3rd pillar: private savings (3a and 3b)
Pillar 3a contributions are tax-deductible up to a legal limit, with a bank or an insurer. Pillar 3b is more flexible. More about the 3rd pillar (in French).
Why a broker
Independent advice, at no cost to you
- Free for you: we are paid by the insurers, transparently, as Swiss law requires. Your premiums are not higher than buying directly.
- Independent: a non-tied intermediary registered with FINMA, working for you, not for one insurer.
- The whole market: we compare the main Swiss insurers on comparable cover.
- One contact, in English: we deal with the insurers in French for you, including when you have a claim.


Who we help
Expat families
Health insurance for everyone, the right deductible for each person, home and liability cover.
International organisations
What your organisation covers, what it does not, and the gaps worth filling.
Cross-border commuters
Living in France, working in Geneva: LAMal or French CMU, 2nd and 3rd pillar. Our guide (in French).
Entrepreneurs
Company insurance, plus our accounting and tax services and business address in Geneva.
Your broker
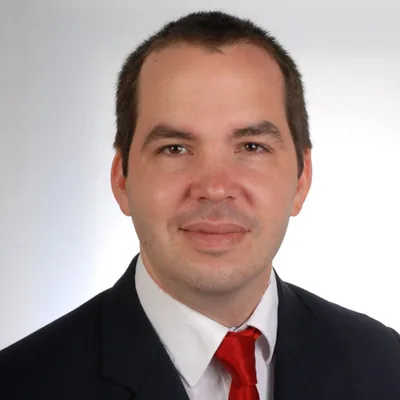
Paul Haran, director of Cologny Conseils
More than 19 years of insurance and pension advice in French-speaking Switzerland. Before running Cologny Conseils since 2017, Paul worked as a financial adviser at AWD (now Swiss Life Select), as a life insurance and tax specialist at Generali, and as a client adviser at Vaudoise Assurances.
He knows the insurers from the inside: their products, their terms and how they handle claims.
Frequently asked questions
General information, checked in October 2026. Your personal situation may change the rules that apply.
Let's sort out your Swiss insurance
Book a free call, message us on WhatsApp or send us your current policies: we reply within one business day.
Prefer a form? Our online request form is in French, but you are welcome to type your answers in English.